
Copper price faces sharp weekly drop as high energy costs bite
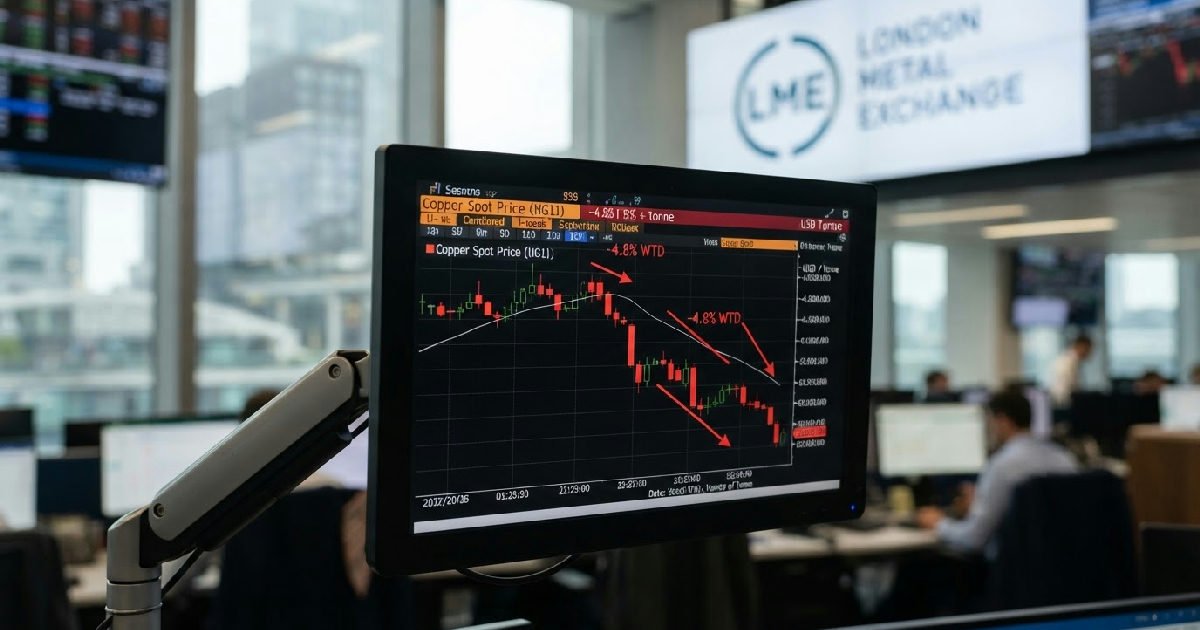
The price of copper is on course for its most significant weekly loss since May, as a trio of economic pressures weighs on the essential industrial metal. Futures on the London Metal Exchange are set to close the week down more than 2%, hurt by soaring energy costs, a resilient US dollar, and troubling signs of industrial weakness in China, the world’s largest consumer.
This downturn casts a shadow over the commodities market, signaling deepening concerns about the trajectory of the global economy. While prices were little changed in Friday’s trading, the week’s overall trend points to a decisive shift in sentiment, as macroeconomic headwinds begin to overpower longer-term supply and demand narratives.
A convergence of bearish signals hits the copper price weekly loss
The recent slide in copper prices isn’t the result of a single factor but rather a confluence of overlapping challenges. Surging oil prices, exacerbated by the latest developments in the Iran war, have a direct impact on the cost of mining, smelting, and manufacturing.
These higher energy inputs squeeze profit margins for industrial users, forcing them to curtail production and, consequently, their demand for raw materials like copper.
Simultaneously, a strong US dollar continues to present a significant hurdle. Because most major commodities are priced in dollars, a stronger greenback makes copper more expensive for buyers holding other currencies. This currency effect acts as a direct tax on global demand, particularly in emerging markets that are crucial centres for manufacturing and construction activity.
This environment adds another layer of complexity for global firms already facing scrutiny on China growth and its impact on supply chains.
Adding to the bearish case are fresh data points indicating a slowdown in China’s vast industrial sector. After a period of tentative recovery, signs of sputtering momentum have re-emerged, spooking investors who rely on Chinese demand to absorb a massive share of global metals output.
Any weakness in China’s economy immediately echoes through the copper market, and the latest figures have done little to inspire confidence.
‘Dr. Copper’ diagnoses a weakening global economy
Copper has long been nicknamed “Dr. Copper” by economists for its uncanny ability to predict the health of the global economy. Its widespread use in everything from housing construction and electrical wiring to consumer electronics and transportation makes its price a sensitive barometer of industrial and economic activity. When copper prices fall, it often signals a coming slowdown.
The current price action is therefore being watched with intense focus by analysts and policymakers. The metal’s decline suggests that businesses are pulling back on investment and expansion plans in the face of economic uncertainty.
This tracks with other worrying indicators, including broader market volatility and stubborn inflation, which have clouded the outlook for the coming months. The combination of these factors points toward a period of lower growth or even potential recession in key economic blocs.
This role as a leading indicator is what separates copper from many other commodities. While oil prices are often swayed by geopolitical events and gold by monetary policy, copper’s value is fundamentally tied to the physical economy—the act of building, manufacturing, and consuming. Its current weakness provides a tangible warning that the global economic engine may be losing steam.
The long-term electrification paradox
Despite the gloomy short-term outlook, the copper market is underpinned by a powerful long-term demand story centered on the global transition to green energy. Electrification is incredibly copper-intensive. An electric vehicle, for example, can contain up to four times more copper than a traditional internal combustion engine car. This demand extends to the charging infrastructure required to support them.
Furthermore, renewable energy sources like wind and solar power demand significantly more copper per megawatt of installed capacity than conventional power plants. Upgrading national power grids to handle this new, decentralised energy flow will also require vast quantities of copper wiring and components. This structural demand creates a fundamental tension in the market, pitting immediate cyclical fears against a long-term, secular bull case.
Persistent supply-side constraints
While demand is facing headwinds, the supply side of the copper equation remains tight. Major producing mines are aging, leading to lower ore grades and higher extraction costs. Bringing new large-scale mines online is a lengthy and capital-intensive process, often taking a decade or more from discovery to production. It’s also fraught with political and environmental hurdles.
Geopolitical instability in key producing regions, such as Chile and Peru, adds another layer of supply risk. Labour strikes, community protests, and proposed changes to tax and royalty regimes can all disrupt production with little warning.
This constrained supply backdrop provides a floor for prices and suggests that any significant and sustained increase in demand could quickly lead to a market deficit and a sharp price rebound.
Market sentiment and the path forward
The mood on the London Metal Exchange reflects this complex dynamic. While the weekly trend is sharply negative, the fact that prices stabilised on Friday suggests traders are taking stock of the competing narratives. The market appears caught between the immediate reality of weakening demand and the widely accepted forecast of a future supply gap driven by electrification.
For now, macroeconomic fears are firmly in the driver’s seat. Investors will be closely watching upcoming inflation reports, central bank statements, and, most critically, purchasing managers’ index (PMI) data from China and Europe. These figures will provide the next major clues about the health of the global industrial sector and the likely path for short-term copper demand.
The outlook is further complicated by the performance of related industrial sectors. Weakness in automotive manufacturing or construction directly impacts copper consumption. The challenges facing both consumer and industrial demand for big-ticket items create a feedback loop that reinforces the bearish sentiment currently dominating the metals market.
Ultimately, the path for copper prices in the coming year will be determined by which force proves stronger: the cyclical slowdown driven by high energy costs and interest rates, or the structural demand boom promised by the green energy transition. For the moment, the doctor’s diagnosis is one of caution.