
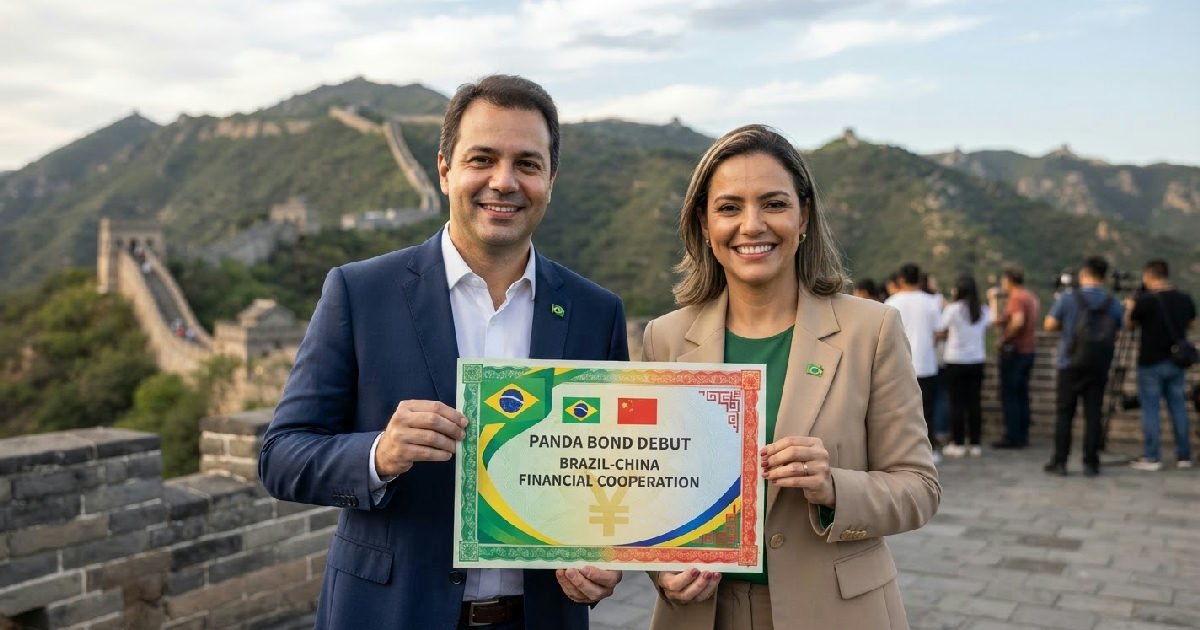
Brazil readies landmark yuan bond debut in China June 2026
Brazil is poised to launch its inaugural yuan-denominated bond sale in China as early as next week, marking a significant milestone in its financial strategy and cementing closer economic ties with Beijing.
The anticipated “Panda bond” debut will see Brazilian finance officials finalize details in China, with the renminbi-denominated debt potentially hitting the market as early as next week, as finance officials iron out the final details in China.
Brazil China bond debut: pivô estratégico
This move is more than just a new funding avenue; it represents a strategic shift for Brazil to diversify its international financing sources away from traditional dollar-denominated markets. It also underscores China’s ongoing efforts to internationalize its currency, the renminbi, by making its onshore bond market more accessible to foreign sovereign issuers.
The upcoming Panda bond issuance is the culmination of years of deepening financial and trade relations between Brazil and China. China has been Brazil’s largest trading partner since 2009, with bilateral trade soaring from $3.2 billion in 2001 to an impressive $158 billion in 2024. Both nations are key members of the BRICS bloc and the G20, advocating for a more multipolar global financial system.
Brazil formally initiated the process for its first sovereign issuance of yuan-denominated bonds on June 25, 2026, making it the first Latin American country to undertake such a move. Finance Minister Dario Durigan and Deputy Secretary for Public Debt Francisco Segundo have been instrumental in this initiative, working closely with Chinese regulators like the People’s Bank of China (PBOC) Governor Pan Gongsheng.
Deepening economic ties between two BRICS nations
The groundwork for this bond debut has been laid through several high-level engagements. A pivotal moment came in May 2025 during Brazilian President Luiz Inácio Lula da Silva’s visit to Beijing, which yielded 36 agreements spanning infrastructure, finance, and industrial cooperation. Central banks from both countries also signed a memorandum of understanding on financial strategic cooperation, setting the stage for deeper integration.
Subsequent meetings, such as the 11th and 12th China-Brazil Financial Subcommittee gatherings in September 2025 and June 2026, further hammered out the details of expanding financial collaboration. These discussions covered a range of topics, including trade in local currencies, sovereign bond issuance, and green economy initiatives, signaling a comprehensive partnership strategy.
Milestones in financial cooperation
Beyond bond markets, Brazil and China have steadily integrated their financial systems. In August 2026, the two nations finalized a bilateral agreement to establish a direct clearing system. This landmark system allows trade contracts to be settled directly in Chinese Yuan (RMB) and Brazilian Real (BRL), bypassing the US dollar and further reducing reliance on Western financial infrastructures.
This initiative follows Brazil’s announcement in August 2026 of plans to issue yuan-denominated bonds annually. Such a commitment aims to embed the Chinese currency permanently into Brazil’s external debt strategy. Initial reports suggest the first issuance could target around 5 billion yuan, equivalent to roughly $735 million.
Understanding Panda bonds and their market
Panda bonds are renminbi-denominated debt instruments issued by non-Chinese entities within the People’s Republic of China’s onshore bond market. They differ fundamentally from “Dim Sum bonds,” which are issued in offshore markets, predominantly Hong Kong. The concept was introduced in October 2005, with the International Finance Corporation and the Asian Development Bank being among the initial issuers.
Initially, funds raised through Panda bonds were often restricted to use within China. This significant limitation was lifted in May 2010, broadening the appeal of these bonds to international issuers seeking renminbi funding for global operations. The change made Panda bonds a more flexible tool for foreign entities looking to tap China’s vast capital market.
Evolution of China’s onshore bond market
The Panda bond market has experienced substantial growth and evolution, becoming an increasingly important segment of China’s financial landscape. Issuance reached a record RMB 194.8 billion in 2024, demonstrating robust global interest. The first half of 2026 alone saw approximately RMB 160 billion in issuance, marking a 68% year-on-year increase, with the total outstanding volume surpassing RMB 500 billion by July.
This expansion reflects China’s strategic push to deepen its capital markets and enhance the global standing of the renminbi. For international issuers, accessing this market offers diversification, a new investor base, and often competitive financing costs, particularly when China’s monetary policy is expansionary.
Global precedents for yuan-denominated debt
Brazil isn’t trailblazing alone, as several other sovereign governments have previously tapped the Panda bond market. Poland became the first European sovereign to issue Panda bonds in June 2016, a move that paved the way for others. Following suit, the Philippines issued its inaugural Panda bonds in March 2018, becoming the first ASEAN member to do so.
More recently, Pakistan issued its first Panda bond in May 2026 as part of a broader $1 billion program aimed at diversifying its funding sources. These precedents highlight a growing global trend among nations seeking to reduce their reliance on traditional dollar funding and embrace alternative capital markets for their debt needs.
For more on how global financial instruments are evolving, read about CME Group launches Bitcoin Cash and Uniswap futures.
Expert perspectives on diversification and cost advantages
Analysts widely view Brazil’s foray into the Panda bond market as a shrewd financial move. It allows the South American nation to tap into the world’s second-largest bond market, significantly expanding its investor base beyond conventional Western financial centers. This diversification is critical for long-term fiscal stability and resilience against regional market fluctuations.
Beyond broadening its investor pool, Brazil stands to benefit from potentially lower financing costs. China’s generally more expansionary monetary policy has often kept yuan-denominated borrowing costs below those in dollar-denominated markets. This cost advantage, coupled with the relative stability of the Chinese currency, can also lead to reduced hedging expenses for international issuers.
Cost-effective financing in an expansionary environment
Brazil’s Finance Minister Dario Durigan emphasized that the initiative serves as a “test.” He noted that a successful sovereign issuance could pave the way for Brazilian companies to deepen their presence in China’s capital markets and potentially offer a hedge against currency volatility for Brazilian investments already denominated in yuan. This strategic approach aims for both direct financial benefits and broader economic advantages.
From Beijing’s perspective, the move is equally welcomed. People’s Bank of China Governor Pan Gongsheng has expressed that China encourages more qualified Brazilian institutions to engage with its financial markets. The PBOC remains ready to facilitate Brazil’s Panda bond issuance, signaling China’s commitment to supporting global investors and issuers in accessing its burgeoning financial ecosystem.
Establishing a sovereign yield curve in yuan
A key strategic objective for Brazil is to establish a sovereign yield curve in yuan. This would provide a crucial benchmark for Brazilian companies looking to raise funds in the Chinese currency, making it easier for them to price their own yuan-denominated bonds and access Chinese investors. This could unlock substantial capital for Brazilian businesses seeking to expand or operate in Asia.
The sovereign issuance sets a precedent and builds confidence. While companies like Suzano, a Brazilian pulp and paper producer, have already issued multiple Panda bonds since 2024, raising 2.6 billion yuan across three transactions, a sovereign bond offers a risk-free rate that other corporate bonds can price against. This fosters a more mature and accessible market for future Brazilian issuers.
Forward outlook: regular issuance and reduced dollar dependence
Brazil’s commitment extends beyond this initial issuance. The country plans to make yuan-denominated bonds a permanent feature of its external debt strategy, with intentions for annual issuances. This long-term vision aims to solidify the renminbi’s role in Brazil’s financial planning and further reduce its historical reliance on the US dollar as the primary reserve and transaction currency.
The successful integration of yuan bonds into Brazil’s debt portfolio could also inspire other Latin American nations to explore similar diversification strategies. This shift represents a broader geopolitical and economic realignment, potentially fostering greater financial autonomy for emerging markets.
New avenues for green investments
Brazil is also leveraging its engagement with China to attract investments for its ecological transition initiatives. The Brazilian government has presented opportunities under “Eco Invest Brasil,” a program designed to mobilize private capital for sustainable projects. This aligns with Brazil’s Sovereign Sustainable Bond Framework, launched in September 2023, which aims to raise funds for programs with positive environmental and social impacts.
China, a major investor in green technologies and infrastructure, represents a significant source of capital for these ambitious environmental projects. Tapping into the Chinese bond market could provide a robust funding mechanism for Brazil’s climate goals, connecting its sustainability agenda with a vast pool of environmentally conscious investors.
Such financial shifts are part of a wider trend in global markets, including extended options trading hours.
Navigating potential risks and future implications
While the benefits are considerable, issuing debt in yuan does introduce certain risks for Brazil. The primary concern is exposure to exchange rate fluctuations between the Chinese currency and the Brazilian real. Managing these currency risks through hedging strategies will be crucial for maintaining the value of these debt obligations and avoiding unexpected costs.
Furthermore, navigating the Chinese financial market requires familiarity with its unique regulatory framework and the greater state participation compared to Western markets. While China is actively opening its markets, issuers like Brazil will need to adapt to these specific conditions. Nonetheless, this historic move is set to reshape Brazil’s financial landscape and deepen the South-South economic corridor.