
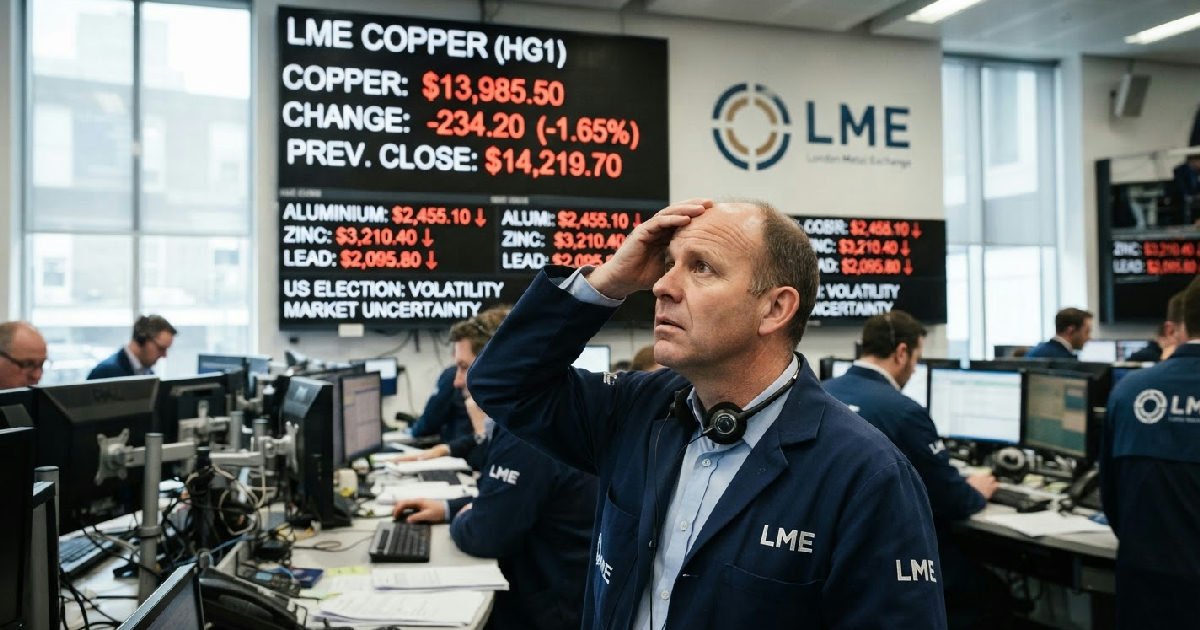
copper prices slip on US midterm election uncertainty
Copper, often seen as a key indicator for the global economy, has slipped further below the critical $14,000 per metric ton mark on 2026-11-04, extending a two-day losing streak. The metal closed down 2.1% at $14,034 per metric ton on November 3 on the London Metal Exchange (LME), having touched an 11-week low of $13,883.
This decline comes amidst heightened market anxiety following early US midterm election results, which suggest a growing possibility of a Democratic sweep of Congress. This political shift is casting a shadow over technology stocks and future artificial intelligence (AI) spending, areas vital for copper demand.
Why Copper Prices Slip
The metal, indispensable in data centers, power transmission infrastructure, electric vehicles, and renewable energy systems, found itself under renewed pressure as broad stock market indices faltered. Investors are now closely scrutinizing the potential policy implications of a significantly altered legislative landscape. The uncertainty has prompted a cautious approach across industrial metals markets, dampening overall risk appetite.
The 2026 US midterm elections, held on November 3, saw all 435 House seats and 35 Senate seats contested during President Donald Trump’s second term. Initial results hint at a strong Democratic showing, leading to speculation about a potential sweep of both legislative chambers. This outcome presents a mixed bag for financial markets, particularly those sensitive to shifts in fiscal policy and regulatory environments.
Historically, midterm elections introduce a period of market volatility, but a decisive outcome can sometimes provide clarity. However, the current expectation of midterm election gridlock or a significant shift in power is leading to investor caution. Such a scenario could impact everything from infrastructure spending initiatives to corporate taxation policies, directly influencing industrial demand for commodities like copper.
Prediction markets strongly favor Democrats winning the House and give them about a 70% chance of controlling both chambers. A Democratic-controlled Congress could lead to increased regulatory scrutiny on various industries, including AI companies, banks, and cryptocurrency firms. This might indirectly reduce capital expenditures and investment, impacting sectors that rely heavily on copper.
The prospect of a Democratic sweep has investors assessing the broader economic impact. For the copper market, which thrives on robust industrial activity and stable economic growth, this political uncertainty translates into downward price pressure. This dynamic underscores how deeply entwined political landscapes are with global commodity valuations.
AI spending jitters hit copper demand forecasts
Beyond the immediate political fallout, concerns surrounding future AI spending are significantly impacting copper’s valuation. The metal has been a key beneficiary of the burgeoning AI sector, given its extensive use in the electrical components, wiring, and cooling systems required for advanced data centers. However, a recent rout in technology stocks has triggered widespread jitters regarding capital expenditures in the AI space.
Marex analyst Ed Meir noted that copper appears to be “catching up” to the broader decline observed in the AI semiconductor group. This suggests that the market is now pricing in reduced expectations for near-term copper consumption tied to AI infrastructure expansion. The perception of slowing investment or tighter regulatory frameworks could directly translate into diminished orders for the red metal.
The expansion of artificial intelligence infrastructure was once a strong demand catalyst for copper. Data centers, for example, require significant amounts of electrical equipment and power connections. Any apprehension about AI-related capital expenditures, driven by economic uncertainties or regulatory changes, dampens expectations for near-term copper consumption.
This dynamic highlights copper’s dual role: not only as an indicator of traditional industrial health but increasingly as a proxy for the high-tech sector’s expansion. Any slowdown in technology-driven growth, whether due to economic headwinds or policy shifts, disproportionately affects copper’s outlook. The rapid expansion of AI infrastructure, once a primary growth driver, now faces a period of re-evaluation by investors.
Copper: a historical economic barometer
Copper has long been dubbed “Dr. Copper” by analysts, a nickname reflecting its perceived ability to predict turning points in the global economy. Its widespread use across various industries makes its price highly sensitive to shifts in economic activity. This industrial omnipresence positions copper as a crucial barometer for overall economic health.
The metal is a fundamental component in construction, power grids, and nearly all electronics. Its demand also surges with the growth of electric vehicles (EVs) and renewable energy infrastructure. A decline in copper prices often signals concerns about future industrial production and global economic growth, which is exactly what the current market movement reflects.
The recent price movements, including the drop to an 11-week low, indicate that investors are reacting to more than just political outcomes. They are weighing the potential for broader economic slowdowns that could curtail demand across multiple sectors. This sensitivity underscores why copper prices are so closely watched by economists and financial strategists alike.
Complex global supply and inventory puzzles
Despite the recent price declines, the global copper market presents a complex picture of supply and inventory levels. LME copper stocks (MCUSTX-TOTAL) have seen an increase, rising to a four-month high of 309,650 metric tons. A significant portion of this increase came from an inflow of 17,325 tons of copper into LME-registered warehouses in the United States, further weighing on market sentiment.
However, beneath the headline inventory figures, regional discrepancies persist. Approximately 80% of visible global copper inventories are held within the United States. This concentration creates regional shortages elsewhere, particularly in China, the world’s largest consumer. The Yangshan copper premium, reflecting what Chinese buyers pay above benchmark prices, remains near $200 a ton, its highest in over a decade, signaling tight physical supply in that region.
Beyond inventory distribution, several factors contribute to ongoing supply constraints. Operational disruptions and weaker production in Chile, one of the world’s largest copper producers, continue to impact global availability. Maintenance at Chinese smelters and limited scrap availability further tighten the physical market, adding layers of complexity to the seemingly robust global stock numbers.
This imbalance between globally available stocks and regional supply tightness means that while overall inventory numbers might seem ample, specific markets can still experience significant price pressures. Investors are also monitoring the US-Iran conflict, with implications for global supply chains and commodity flows, adding another layer of geopolitical risk to the intricate supply picture.
Crypto market anxiety is also high, reflecting a broader sentiment of uncertainty.
Future outlook and expert forecasts amid volatility
Despite the current downturn and the uncertainties stemming from the copper midterm elections, several major financial institutions maintain a largely optimistic long-term outlook for copper prices. Morgan Stanley, for instance, forecasts copper to average $14,800 per metric ton in the fourth quarter of 2026. This is approximately 3.9% above a recent LME price of $14,251, suggesting a potential rebound.
Goldman Sachs echoes this positive sentiment, expecting copper to reach $14,700 by year-end and average $15,400 in 2027. J.P. Morgan also projects a fourth-quarter average of $14,800. These forecasts are underpinned by the anticipated long-term demand for copper, particularly from the ongoing global energy transition and the expansion of data-intensive technologies.
However, short-term volatility remains a key characteristic of the market. Copper’s recent decline below its 100-day moving average at $14,054 has reinforced bearish momentum, turning that level into resistance. Initial support is now seen at the 200-day moving average, around $13,589. This technical indicator suggests that while the long-term fundamentals are strong, the immediate path for copper could be turbulent.
The market also faces broader economic headwinds, including concerns over slowing global economic growth. The interplay of political outcomes, technological investment patterns, and fundamental supply-demand dynamics will continue to define copper’s trajectory in the coming months. Marshall Wace funds, among others, have felt the impact of broader market volatility.