
Moody’s Q3 earnings of $4.14 miss estimates
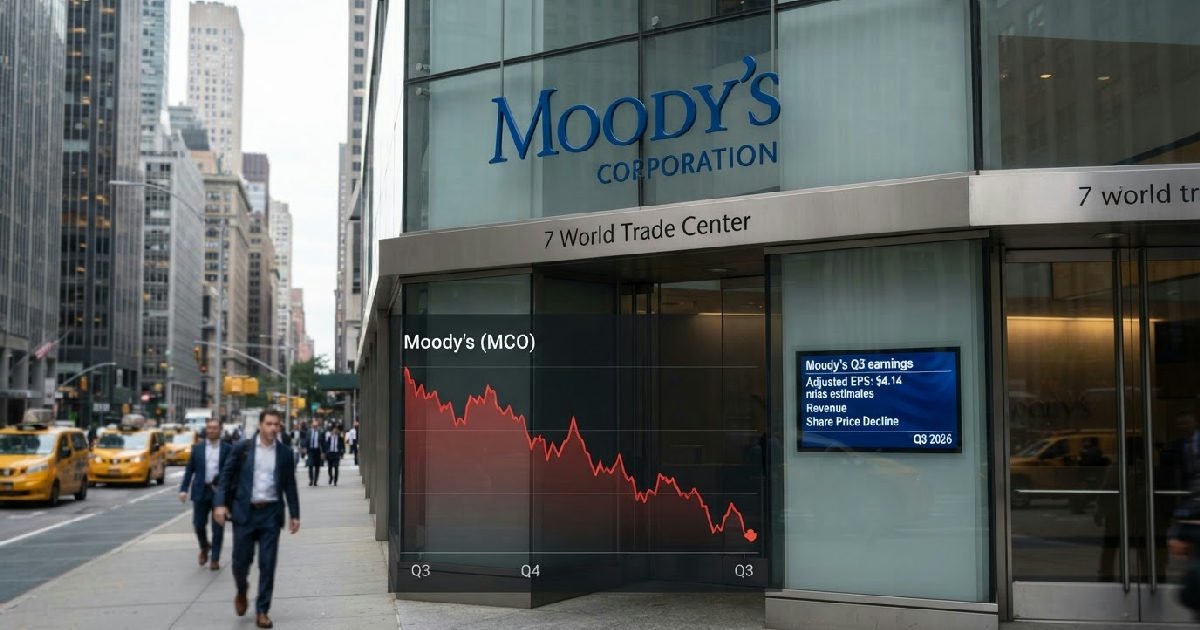
Moody’s Corporation (NYSE: MCO) saw its shares decline on Wednesday after reporting third-quarter financial results that fell short of Wall Street estimates. The global risk assessment firm announced on October 21, 2026, that a slowdown in its core ratings business, pressured by rising yields and sluggish corporate bond issuance, dragged down its overall performance, impacting Moody’s Q3 earnings.
The New York-based company posted adjusted earnings of $4.14 per share, missing the median analyst forecast of $4.27. Revenue for the quarter came in at $2.02 billion, likewise failing to meet the consensus estimate of approximately $2.08 billion. The news provides a detailed look into the challenges facing financial services firms, similar to other recent Q3 earnings reports that have captivated investors.
Analyzing Moody’s Q3 earnings figures
While the headline numbers signaled a miss, the details paint a more complex picture. Total revenue of $2.02 billion represented a marginal 1% increase from the $2.01 billion reported in the same period last year. On an organic, constant currency basis, which strips out the effects of foreign exchange fluctuations and acquisitions, revenue growth was slightly healthier at 3%.
The company’s net income attributable to the firm was $734 million, or $4.24 per diluted share, an increase from the prior year’s $646 million, or $3.60 per share. Despite the rise in net income, profitability metrics faced pressure.
Moody’s adjusted operating margin contracted by 30 basis points to 52.6% from 52.9% in the third quarter of 2025. This tightening margin reflects the difficult operating environment that President and Chief Executive Officer Rob Fauber acknowledged, stating the company delivered “strong profitability and earnings growth, with disciplined execution and healthy cash generation amidst an increasingly complex operating environment.”
The market’s reaction was swift. Following the announcement, shares of Moody’s fell 2.81%. The negative sentiment had already been brewing, with premarket trading showing a 0.61% dip to $472.43 per share, highlighting investor anxiety ahead of the official release.
A tale of two business segments
The company’s performance underscores a growing divergence between its two primary divisions: the cyclical Moody’s Investors Service (MIS) and the subscription-driven Moody’s Analytics (MA). The earnings miss was almost entirely concentrated in the ratings business, which has long been the firm’s marquee earnings engine but remains heavily dependent on debt issuance volumes.
Revenue for Moody’s Investors Service, the segment responsible for credit ratings, fell by 1% year-over-year to $1.09 billion. The company attributed this decline to lower leveraged finance issuance compared to a particularly strong period in the previous year. This cyclical vulnerability is a key concern for investors, as rising interest rates can dampen corporate appetite for new debt, directly impacting MIS revenue streams.
Bright spots in ratings and analytics
However, it wasn’t all bad news for the ratings division. The segment saw an 18% growth in investment-grade revenue, indicating healthy activity from blue-chip corporations. More significantly, first-time mandates—a key indicator of future business—surged by 40%, marking the strongest quarterly total for this metric in five years. This suggests a robust pipeline of new clients even as the broader issuance market cools.
In stark contrast to the ratings segment, Moody’s Analytics continued its steady growth trajectory. The analytics division, which provides data, software, and risk-management tools, saw revenue climb 3% to $936 million. On an organic, constant currency basis, its growth was a more impressive 8%.
This performance highlights the success of Moody’s strategy to build a more stable, recurring revenue base to offset the volatility of its ratings business. Recurring revenue now accounts for a staggering 99% of the analytics segment’s total. Annualized recurring revenue is up 8% to $3.7 billion, and the division boasts a strong customer retention rate of 95%.
Company guidance and market outlook
Looking ahead, Moody’s reaffirmed its full-year guidance for 2026, but the details suggest a cautious stance. The company maintained its projection for adjusted earnings per share in the range of $16.50 to $17.00. However, the midpoint of this range, $16.75, sits just below the current analyst consensus of $16.90.
This subtle discrepancy signals that the company may not expect a significant rebound in the final quarter, underscoring a cautious approach amid broader economic uncertainties. The broader economic climate has influenced corporate earnings reports across various sectors.
The company also maintained its forecast for high-single-digit percentage revenue growth for the full year. This guidance relies heavily on the continued strength of the Moody’s Analytics division to counteract any further weakness in debt issuance markets.
The firm also plans to continue rewarding shareholders, with up to $3 billion in share repurchases guided for the full year. Year-to-date, Moody’s has already returned approximately $3.1 billion to shareholders, including $2.6 billion in share repurchases.
The performance of the leveraged finance market remains the most significant variable for Moody’s heading into 2027. While the company’s 2026 outlooks pointed to generally stable corporate credit conditions, it also highlighted downside risks from volatile trade policy and a cooling economy.
The future of corporate bond sales will be a critical factor in determining if Moody’s can meet its growth targets and restore investor confidence.
Strategic shift toward integrated risk assessment
The Q3 results reinforce the strategic importance of Moody’s evolution from a pure credit rating agency into a global integrated risk assessment firm. The consistent growth of the Moody’s Analytics segment provides a crucial buffer against the inherent cyclicality of the ratings business. This diversification strategy, focused on subscription-based data and software, is designed to deliver more predictable revenue streams.
This quarter’s performance shows the strategy is working as intended, though perhaps not yet at a scale to completely offset a significant downturn in debt markets.
The strong growth in annualized recurring revenue and high retention rates within the analytics division demonstrate a sticky customer base and a valuable product offering that extends beyond traditional credit ratings into areas like cyber, compliance, and supply chain risk.
As investors assess the stability of the global financial sector, attention remains on major bank earnings and other key economic indicators.
Analysts will be closely watching whether the impressive 40% growth in first-time rating mandates can translate into sustained revenue for the MIS division in the coming quarters. If this pipeline converts successfully, it could help mitigate the impact of lower overall issuance volumes.
For now, investors are weighing the stability of the analytics business against the headwinds facing the more profitable, but more volatile, ratings franchise.