
Global Markets Defy Mideast Tensions as Oil Declines
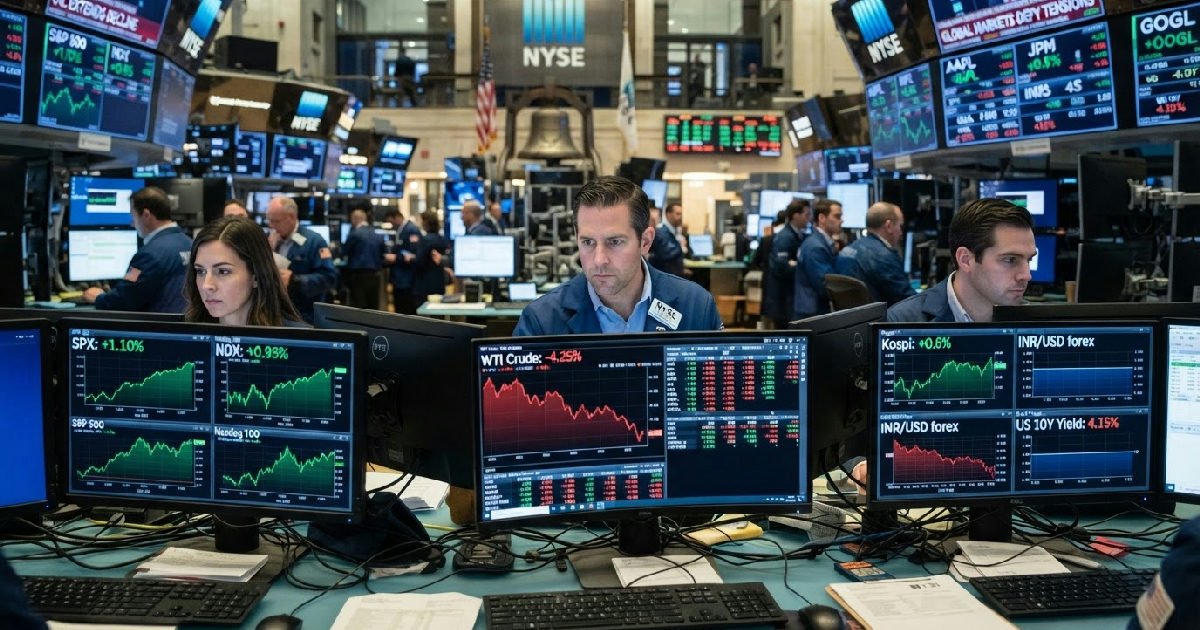
Global financial markets exhibited a notable resilience on October 12, 2026, as stock and bond futures registered gains while crude oil prices unexpectedly extended their decline. This occurred despite a fresh wave of attacks in the Middle East that analysts feared could escalate regional conflicts and disrupt energy supplies.
Traders seemingly chose to look beyond the immediate geopolitical concerns, focusing instead on upcoming economic indicators. This market behavior signals a complex interplay of factors influencing investor sentiment, from regional instability to broader macroeconomic trends.
Global markets navigate Mideast volatility with caution
Despite recent Houthi strikes on Saudi Arabia, major market indices showed upward momentum. Futures for the S&P 500 Index and the Nasdaq 100 Index both climbed by at least 0.3%, indicating a robust start to the trading week in the US.
Bond markets also found footing, with Treasury futures reversing earlier losses to edge higher. Similarly, government bonds in Australia and New Zealand saw modest gains, reflecting a broader interest in safer assets amidst global uncertainties.
Crude Oil’s Unexpected Dip
Contrary to expectations, Brent crude oil prices fell 1.7% to $102.99 a barrel, moving down from an earlier high of $105.63. This decline surprised many, given the direct threats to oil infrastructure and shipping in the Gulf region.
This unexpected dip follows a period where Brent crude prices had climbed notably, including a 5% rise to $105.3 a barrel on Thursday, October 8, 2026. Earlier surges saw Brent crude advance more than 70% since the start of 2026.
Mixed Signals from Asian Equities
Asian equity benchmarks presented a mixed picture. South Korea’s Kospi experienced a significant slide, dropping 1.7% as trading resumed after a long holiday weekend, highlighting regional sensitivities to market shifts.
The broader MSCI Asia Pacific Index also saw a slight dip, down 0.1%, underscoring a cautious sentiment across diverse economies in the region. Meanwhile, the Indian rupee notably climbed in offshore trading, reflecting specific regional currency dynamics.
Escalating Tensions in the Middle East
The latest market movements unfolded against a backdrop of renewed and significant geopolitical risks in the Middle East. Yemen’s Houthi rebels launched weekend strikes on Riyadh’s main airport in Saudi Arabia, a move that heightened regional instability.
These attacks, which involved missile strikes on Riyadh’s main airport, occurred over the weekend of October 10-11, 2026. They reportedly caused casualties and disrupted airport operations, marking a significant escalation, and followed a period where the Houthis had largely remained uninvolved in the broader US-Israeli conflict against Iran that began in February.
Direct Threats to Energy Infrastructure
The Houthi aggressions extended beyond the airport, with claims of strikes against Dammam airport and Saudi Aramco facilities. Additionally, the weekend saw two tankers attacked—one by a drone near Oman, and another damaged in the Strait of Hormuz.
These incidents revived concerns about the security of oil supply lines from the Middle East, a critical region for global energy markets. Such attacks have reached their highest frequency since the onset of the US-Israel war with Iran earlier this year.
International Reaction and Regional Fallout
The attacks drew strong international condemnation, with US President Donald Trump calling them “unacceptable” and hinting at potential US military involvement alongside Saudi Arabia. US Secretary of State Marco Rubio also criticized the “blatant disregard for innocent civilian life.”
Saudi Arabia has pledged a “decisive response” against the Houthis, indicating a potential for further escalation. The broader conflict involving the US and Israel with Iran, which commenced in February 2026, continues to cast a long shadow over regional stability and corporate investment strategies.
Driving Factors Beyond the Conflict
While geopolitical tensions remained a significant undercurrent, traders also looked ahead to crucial economic data. Upcoming inflation data releases in the US and Europe are expected to provide clearer direction for central bank policies and interest rate trajectories.
Oil prices, despite their current decline, are widely considered a pivotal element in the outlook for interest rates, as persistent energy costs can fuel inflationary pressures. This makes the recent dip in crude particularly noteworthy for its potential implications.
Inflation and Interest Rate Implications
Central banks globally are grappling with inflation, making any shifts in key commodity prices critical. A sustained decline in oil could offer some breathing room, potentially easing pressure for aggressive interest rate hikes.
Conversely, a sudden reversal in oil trends could quickly reignite inflation concerns, complicating monetary policy decisions. These dynamics create a volatile environment for investors and policymakers alike, demanding constant vigilance.
Central Bank Interventions and Currency Stability
Beyond the major economies, India’s central bank recently implemented some of its most substantial measures to bolster the rupee since the 2013 taper tantrum. Such proactive steps highlight the global sensitivity to market fluctuations and geopolitical events.
Interventions by central banks often reflect underlying anxieties about economic stability. These actions can also provide critical support for local currencies amidst broader international market turbulence.
Analyst Perspectives and Future Outlook
Market analysts are closely watching the confluence of geopolitical events and economic data. Nick Twidale, chief market analyst at AT Global Markets in Sydney, emphasized that the impending US inflation reading and the start of another earnings season mean “there will be plenty for markets to digest.”
This sentiment underscores the multi-faceted challenges facing investors. Markets aren’t just reacting to single events but to a complex web of interconnected global phenomena, from regional wars to national economic performance.
The Enduring Influence of Oil Prices
Historically, major geopolitical events have often triggered significant oil price volatility, influencing broader market sentiment. While the immediate reaction saw oil decline despite Middle East attacks, the long-term impact remains a key concern.
For instance, past shocks like the 1973 Arab-Israeli War or the 1990-1991 Gulf War led to substantial price increases and macroeconomic contractions. Analysts from Goldman Sachs have previously raised their Brent crude forecast, estimating a risk premium of over $20 a barrel due to potential escalation.
Upcoming Market Catalysts
With US markets, including cash trading in Treasuries, closed for holidays on Monday, the full extent of investor reaction remains to be seen later in the week. The coming weeks will provide clearer indications of how these diverse factors will ultimately shape asset valuations and economic forecasts worldwide, including the growth of institutional financial products.