
Europe power surge returns amid geopolitical concerns
Europe’s electricity markets are flashing their strongest warning signs since the 2022 energy crisis, as the continent braces for winter. A significant Europe power surge in wholesale electricity prices, especially in Germany, indicates escalating costs driven by surging natural gas prices and heightened geopolitical tensions. This re-emerging vulnerability is casting a long shadow over the continent’s energy security outlook.
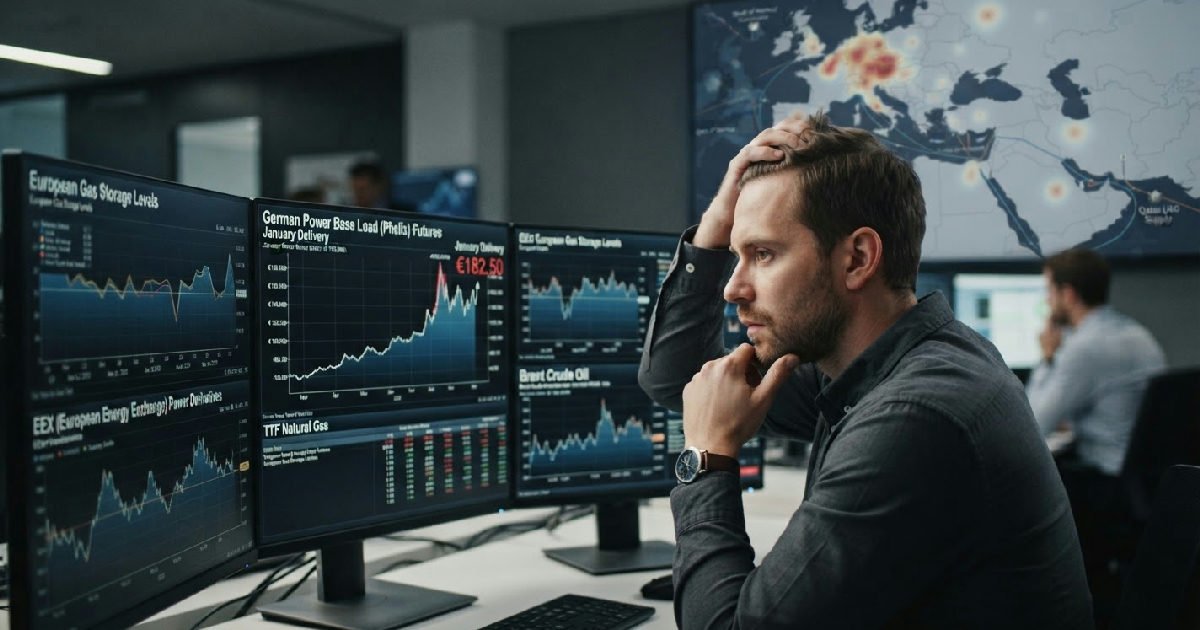
Wholesale power for January delivery in Germany, the region’s economic powerhouse, is now trading above €180 a megawatt-hour on the European Energy Exchange. This marks a stark increase of more than 60% compared to a year ago, reflecting acute pressure on the European grid.
Europe power surge amid renewed energy pressures
Natural gas, a critical fuel source, has seen recent price spikes, complicating efforts to refill Europe’s strategic storage facilities amidst fierce global competition.
The current surge in energy prices presents a formidable challenge as Europe pushes to electrify its economy and reduce reliance on imported fossil fuels. Analysts are closely watching these market movements, drawing comparisons to the dramatic cost increases observed just two years prior. The financial burden will likely affect both industrial operations and household budgets.
Geopolitical developments have undeniably compounded the market’s unease. The ongoing Iran war, for instance, has directly impacted global energy flows, disrupting crucial supply routes. The closure of the Strait of Hormuz, a vital maritime chokepoint, has severely hampered the delivery of liquefied natural gas (LNG) from Qatar to international buyers.
Natural Gas Fuels Price Escalation
Natural gas remains the single largest determinant of European electricity prices, and its volatility is once again a major concern. The market has reacted sharply to supply constraints and demand forecasts, leading to rapid price appreciation. This dynamic underscores Europe’s continued susceptibility to global gas market fluctuations.
The intricate web of international trade and energy production means that disruptions in one area can quickly translate to challenges elsewhere. This global supply chain instability impacts various economic sectors across Europe. European businesses, facing increased operational expenses due to energy costs, are particularly vulnerable.
Soaring wholesale gas prices
European natural gas, specifically the Title Transfer Facility (TTF) benchmark, was recorded at €81.07 per megawatt-hour on September 16, 2026. This figure follows an annual high of €83.97 per megawatt-hour just one day earlier, demonstrating significant upward momentum. These elevated price points have not been observed consistently since late 2022.
The current TTF levels represent a staggering 187% increase compared to the beginning of the year. Such rapid escalation puts immense strain on energy providers and downstream industries. It highlights the swift and dramatic impact that natural gas pricing can have on the wider European economy.
Impact of storage levels
Europe’s gas storage levels currently sit below crucial benchmarks, intensifying fears over winter supply security. As of September 15, 2026, European Union gas storage stood at 68.49% of capacity. This is markedly lower than the 80.83% recorded on the same date in 2025.
Furthermore, current levels are significantly below the more robust figures exceeding 93% seen in both 2023 and 2024. Morningstar, an independent investment research firm, projects that EU gas storage will reach an “all-time low” of 69% by November 1, 2026. This forecast indicates the lowest storage levels since the 2021-2022 energy crisis.
Echoes of the 2022 Energy Crisis
The current market instability draws uncomfortable parallels with Europe’s severe energy crisis between 2021 and 2023. That period was characterized by an unprecedented confluence of factors that sent prices soaring. It served as a harsh lesson in energy dependency and market vulnerability.
A rapid post-COVID-19 demand surge in 2021, coupled with reduced natural gas supplies from major exporters like the US, Norway, and Russia, initially triggered the crisis. Russia’s full-scale invasion of Ukraine in February 2022 then weaponized energy, as Moscow drastically cut gas deliveries to the continent. This escalated the situation dramatically.
Wholesale energy prices for both gas and electricity soared by as much as 15-fold from early 2021, reaching historic highs in August 2022. This had devastating consequences for households and businesses, leading to soaring energy bills, rampant inflation, and a noticeable economic slowdown across the European Union.
The EU responded with its comprehensive REPowerEU Plan in March 2022, aiming to reduce reliance on Russian fossil fuels. This strategy focused on supply diversification, boosting renewable energy sources, and enhancing overall energy efficiency. Such proactive measures aimed to prevent a recurrence of the crisis.
Diversification efforts saw the EU rapidly shift away from Russian energy, with new suppliers including the United States, Norway, Algeria, and Australia. Projections indicated a significant drop in Russian LNG and piped natural gas imports, moving from 45% pre-crisis to an anticipated 13% by 2025. A full ban was slated for the end of 2026 for LNG and autumn 2027 for piped gas.
The bloc also implemented a voluntary goal to cut gas demand by 15% from 2017-2021 levels. This initiative successfully achieved a 17% reduction between August 2022 and January 2025. New regulations mandated aggregate gas storage capacity be filled to at least 80% before winter 2022/23, rising to 90% for subsequent winters.
Geopolitical instability, particularly the ongoing Iran war, underscores the fragility of global energy infrastructure. Localized conflicts can have far-reaching effects on international markets and supply chains, as seen with the disruptions in crucial maritime routes.
Iran conflict and Strait of Hormuz
The ongoing Iran war has created significant turbulence in the critical Strait of Hormuz. This narrow waterway, situated between the Persian Gulf and the Gulf of Oman, is an indispensable transit point for a substantial portion of the world’s oil and liquefied natural gas. Its closure or disruption has immediate and severe global repercussions for energy supply.
The implications of the Strait of Hormuz closure are far-reaching, particularly for LNG shipments. This chokepoint is essential for delivering gas from major producers in the Gulf region. Any sustained disruption here forces longer, costlier shipping routes and exacerbates existing supply anxieties.
Qatar LNG implications
Qatar is one of the world’s leading exporters of liquefied natural gas, and much of its supply traditionally transits through the Strait of Hormuz. The reported closure of this strait directly impacts Qatar’s ability to reliably deliver LNG to its international customers, including European nations. This loss of direct supply intensifies competition for alternative sources.
Europe’s increasing demand for LNG to offset Russian gas has left it vying with Asian markets for available cargoes. Any reduction in Qatari supply further tightens an already strained global LNG market. This increased competition inevitably drives up prices for all buyers, pushing Europe’s energy costs higher.
Other factors contribute to the tight supply picture, including reduced output from France’s nuclear fleet. A combination of heat-related issues and worker strikes has intermittently hampered nuclear power generation. This forces greater reliance on gas-fired power plants, further increasing demand for the volatile fuel.
Winter Outlook and Economic Pressures
As Europe heads into the colder months, the outlook for energy consumers appears increasingly challenging. The combination of elevated natural gas prices, diminished storage levels, and ongoing geopolitical instability points towards a winter with persistently high electricity costs. This will undoubtedly impact businesses and households.
For consumers, high electricity bills will likely squeeze disposable incomes and potentially reignite cost-of-living concerns. Businesses, particularly energy-intensive industries, face increased operational expenses that could erode profit margins or lead to production cuts. This economic pressure could hinder the broader European recovery.
The current situation also poses a dilemma for Europe’s ambitious electrification goals. The continent aims to shift towards renewable energy and electric vehicles, reducing its carbon footprint and reliance on fossil fuels. However, persistently high electricity prices could slow this transition by making electrification less economically attractive for consumers and businesses alike.
Policymakers face the difficult task of balancing energy security with affordability and climate targets. While the EU has made significant strides in diversifying its energy mix since 2022, the present winter power surge demonstrates the persistent fragility of the transition period. Adapting to these ongoing global energy market dynamics remains a central challenge.
Energy costs directly influence production expenses for many industries, linking seemingly disparate market movements. This economic reality means that sustained high power prices could have cascading effects throughout Europe’s industrial sectors.