
Capital One Q3 Earnings Exceed Forecasts
Capital One Financial Corporation (NYSE: COF) delivered third-quarter results that surpassed Wall Street expectations on 2026-10-24, driven by robust credit performance and clear evidence that its blockbuster acquisition of Discover is bearing fruit. These strong Capital One Q3 earnings demonstrate the company’s financial health.
The financial giant reported adjusted earnings of $6.69 per share on $16.34 billion in adjusted revenue for the quarter ending September 30, 2026. This performance sent its stock climbing as much as 6.67% to $215 in after-hours trading.
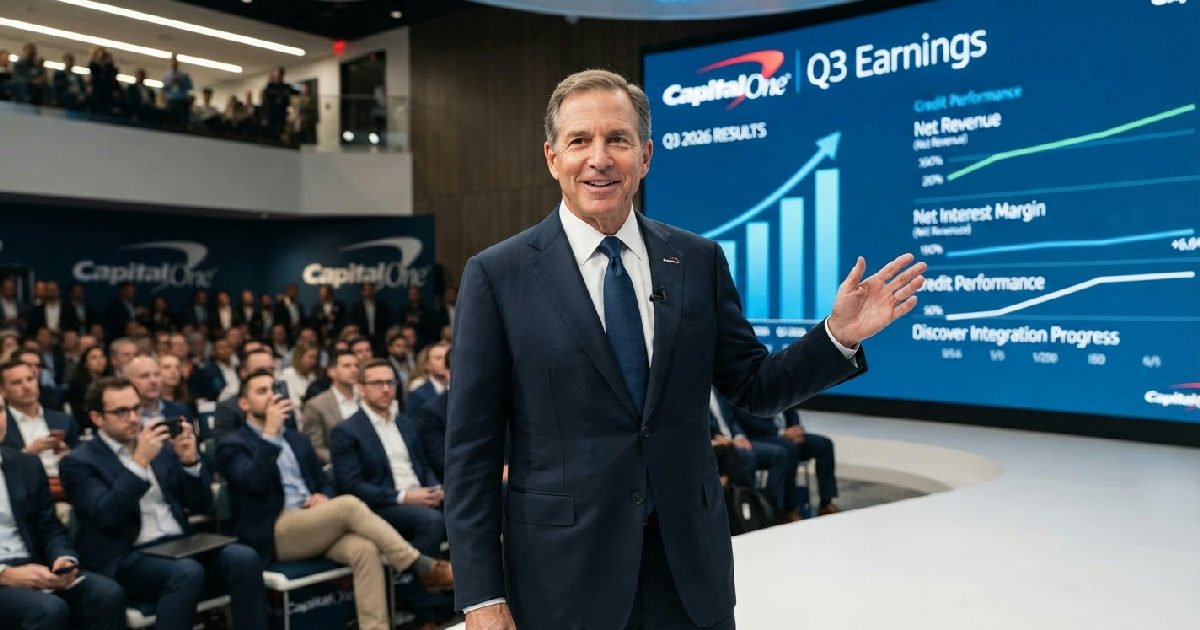
Capital One Q3 earnings report
The positive outcome arrived with the Q3 2026 earnings release on October 20, 2026, followed by a conference call that evening. Capital One’s founder and CEO, Richard D. Fairbank, stated that the earnings power from the Discover acquisition is now clearly visible.
The results handily beat analyst consensus estimates for adjusted earnings per share, which ranged from $5.43 to $5.50. Adjusted revenue also exceeded forecasts, which had ranged from $16.11 billion to $16.26 billion.
The impressive bottom line was fueled by stronger-than-expected net interest income (NII). This figure rose, contributing to a net interest margin (NIM) of 8.41%, an increase of 40 basis points from the prior quarter. This surpasses analyst estimates of 8.2%, indicating the bank is earning more effectively from its loans.
Total net revenue for the quarter reached $16.3 billion, with adjusted revenue at $16.34 billion, representing a 6.4% gain year-over-year and a 3% increase from the prior quarter. Pre-provision earnings, which measure profits before setting aside funds for potential loan losses, jumped 10% from the prior quarter to $7.5 billion.
“Linked quarter revenue increased 3% and noninterest expense declined 2%, resulting in pre-provision earnings growth of 10%,” Chief Financial Officer Andrew Young explained on the call. The bank’s solid capital position was also affirmed, with its Common Equity Tier 1 capital ratio holding steady at 13.8% at September 30, 2026, even after repurchasing $2.6 billion worth of its own shares during the quarter.
Discover Integration Synergies Advance
A central focus for investors has been the integration of Discover Financial Services, an acquisition completed in May 2025. Capital One’s leadership delivered a confident update, with Richard D. Fairbank declaring the process is progressing smoothly and financial benefits are materializing.
He noted that investors no longer need to “hold their breath” to see the deal’s value. “You can squint your eyes and see it now in the first three quarters of 2026,” Fairbank said.
The company’s year-to-date results reflect about $1.8 billion of annualized combined synergies from the merger. Capital One remains on track to achieve the full $2.5 billion in expected merger-related synergies by the second half of 2027. Fairbank confirmed that “the Discover integration continues to go well and we’re making good progress on delivering the expected synergies.”
The initial phase has involved moving Capital One’s debit card volumes onto the Discover network, a process that has already seen approximately 25 million cards converted. The company began converting Discover’s existing credit card portfolio, or “back book,” in July, with additional migration waves scheduled for October and January.
This progress suggests the complex technological and operational merger is on solid footing, crucial for realizing long-term value.
A New Wrinkle in Synergy Realization
While the synergy story was largely positive, Fairbank introduced a notable counterpoint. He anticipates that a proposed legal settlement involving Visa and Mastercard, aimed at lowering merchant swipe fees, will likely impact Capital One’s future interchange revenue.
Fairbank told analysts that this expected revenue loss would be “roughly offsetting” the remaining synergies yet to be realized from the Discover acquisition. This provides a more balanced view of the deal’s net financial impact by 2027.
Strong Credit Quality Boosts Earnings
Despite broader economic anxieties, Capital One’s credit performance was a standout feature, significantly contributing to the earnings beat. The bank’s provision for credit losses—money set aside for potential defaults—was $2.9 billion. This figure was notably lower than the roughly $3.64 billion that analysts had modeled, signaling confidence in the health of its loan book.
The lower provision included a $225 million allowance release, meaning the bank reclaimed funds previously set aside for losses, directly boosting its reported earnings per share. This release was primarily driven by favorable credit performance in its domestic card business. Richard D. Fairbank stated, “Credit’s in a very good place,” noting that delinquencies have been tracking seasonal patterns.
Key metrics underscored this strength. The net charge-off rate improved to 2.73% from 3.23% in Q2 2026. For domestic cards, the charge-off rate fell 73 basis points sequentially to 3.98%. In commercial banking, net charge-offs were zero in the third quarter.
“Our provision for credit losses decreased $73 million or 2% to $2.9 billion,” CFO Andrew Young summarized, attributing it to net charge-offs and the sizable allowance release.
Expense Management and Future Marketing Strategies
Operating costs, specifically non-interest expenses, totaled $8.86 billion, coming in below the almost $9 billion projection. Total non-interest expense decreased 2% to $8.9 billion. These figures include substantial adjusting items related to recent acquisitions, such as $483 million in acquisition amortization expenses and $338 million for Discover integration.
Management flagged heavier marketing spending for 2027, indicating a strategic ramp-up. Capital One expects Q3 to Q4 percentage growth in marketing to be similar to the Q3 to Q4 percentage growth seen in 2025, primarily driven by seasonality. The company plans to “lean back into Discover marketing” in 2027, pursuing growth opportunities across its businesses.
This planned increase in spending will be a key factor for investors to monitor in the coming quarters, as elevated expenses have previously limited the size of near-term earnings beats. Andrew Young noted that net interest margin structural impacts from Discover have largely played out, suggesting future focus may shift to driving volume.
Capital One’s report of $3.5 billion in GAAP net income and strong consumer credit performance provided a sign of stability and strategic execution for investors on Wall Street.