
Lloyds and Visa Settle $750,000 in USDC in Cross-Border Pilot
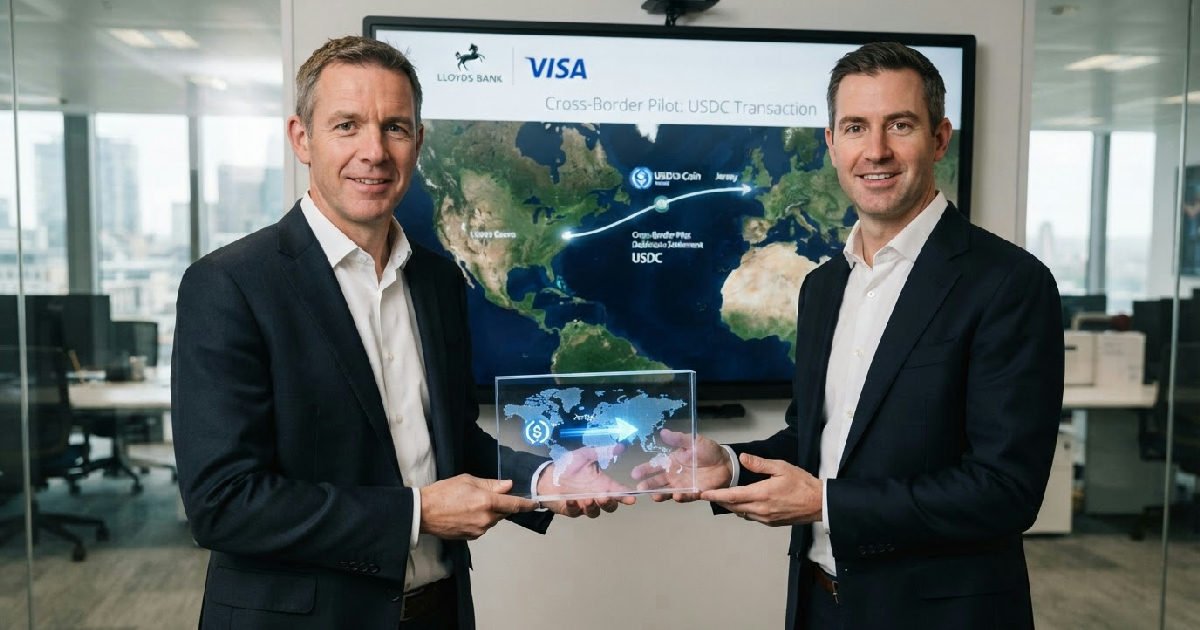
Lloyd’s Banking Group and Visa Inc. successfully completed a seven-day cross-border pilot program, settling US$750,000 in payment obligations using the USDC stablecoin. have completed a seven-day live cross-border pilot program, settling US$750,000 in payment obligations using the USDC stablecoin.
The companies announced on September 30, 2026, that the trial successfully demonstrated round-the-clock cross-border settlement, with funds reaching their destination in under an hour, even over weekends.
This significant collaboration involved the transfer of funds from Lloyds’ Corporate Markets branch in Jersey to Visa in the United States.
Accelerating Institutional Settlement with a Cross-Border Pilot
The seven-day live pilot represents a crucial step for traditional finance in exploring digital assets. It specifically focused on the behind-the-scenes exchange of funds between financial institutions, rather than consumer payments. This could alleviate liquidity challenges faced by businesses due to lengthy traditional settlement processes, which can often take a day or more, particularly outside standard banking hours.
The core objective of the Lloyds Banking Group and Visa pilot was to modernize global money movement, making cross-border transactions faster, more transparent, and more flexible. Stablecoin-based settlement offers a compelling alternative to conventional methods, which typically involve complex networks of correspondent banks and can be prone to delays.
Rob Cameron, Group Country Manager, UK & Ireland, Visa, highlighted the discrepancy between modern business operations and outdated financial infrastructure. Businesses operate globally and continuously, yet traditional money movement mechanisms lack this crucial flexibility. The pilot showcases how stablecoins can bridge this gap.
Interoperability Across Blockchain Networks
The technical architecture of the pilot underscored a commitment to interoperability, leveraging distinct blockchain environments. Lloyds operated its own node on the Canton Network, utilizing its configurable privacy features for the transaction. Visa, meanwhile, supported settlement on a separate public blockchain.
This dual-network approach effectively demonstrated the potential for different blockchain ecosystems to communicate and transact seamlessly. Lloyds acquired the necessary USDC through Archax, a UK-regulated digital asset exchange. This underlines the evolving role of specialist digital asset firms in facilitating mainstream financial adoption.
Lloyds’ Broader Digital Asset Vision
This pilot, however, is not an isolated initiative, but rather a component of Lloyds Banking Group’s extensive exploration into digital assets and tokenized money. The bank aims to integrate these innovations incrementally into existing financial systems, enhancing efficiency for its diverse client base. This aligns with broader financial institution efforts in the digital asset space.
For instance, in December 2025, Lloyds completed a UK-first transaction using tokenized deposits to acquire tokenized UK Government bonds on the Canton Network. This demonstrated the immediate settlement capabilities and the potential to digitize traditional instruments.
Similarly, in July 2025, Lloyds partnered with Aberdeen Investments and Archax to use tokenized real-world assets as collateral for foreign exchange trades on the Hedera Hashgraph blockchain, aiming for improved collateral management and reduced operational costs.
Furthermore, Lloyds is actively collaborating with the London Stock Exchange Group (LSEG) on the Digital Securities Depository (DSD). This on-chain settlement capability, expected to launch in 2026, seeks to deliver greater efficiencies in collateral management, reflecting a systematic effort to embrace distributed ledger technology.
Visa’s Expanding Stablecoin Strategy
Visa Inc. has been a proactive force in the stablecoin space, continuously building out its multichain settlement capabilities. Its strategic vision involves creating a “network of networks” to ensure digital payments remain practical, interoperable, and widely trusted.
The payment giant had previously added Canton Network support to its global stablecoin settlement pilot in April, further cementing its commitment to diversified blockchain integration. These initiatives reflect a dynamic period for the crypto sector, with varied developments spanning institutional settlement to new trading offerings for U.S. traders.
A separate Visa pilot with Brale, leveraging its dollar-backed SBC stablecoin on Canton, was reported in June. These preceding efforts showcase Visa’s methodical approach to testing and validating stablecoin utility for various transactional needs.
Beyond institutional settlement, Visa is also exploring stablecoins for pre-funding and payouts within its real-time payment platform, Visa Direct. A pilot program launched earlier, with limited availability by April 2026, allowed businesses to fund cross-border payments using stablecoins. This initiative aimed to provide businesses with more flexible pre-funding options.
Moreover, in November 2025, Visa announced another pilot designed to enable businesses and platforms to send payouts directly to recipients’ stablecoin wallets. Under this arrangement, recipients could opt to receive USD-backed stablecoins like USDC. This payout-focused pilot was slated for a broader rollout in the latter half of 2026, demonstrating a comprehensive push into stablecoin applications across the payment chain.
The Growing Role of USDC and Regulatory Frameworks
The selection of USDC, a widely recognized stablecoin, for this pilot highlights its perceived reliability and efficiency within the crypto economy. USDC, developed by Circle and Coinbase’s Centre consortium, aims to maintain a 1:1 peg to the U.S. dollar and is backed by highly liquid cash and cash-equivalent assets.
Its reserves undergo regular audits by a Big Four accounting firm, with transparent disclosures provided weekly or monthly.
This transparency and backing are crucial for fostering trust, especially as regulators worldwide scrutinize the digital asset landscape. The global stablecoin market, which reached an estimated market capitalization of over $310 billion by 2026, is predominantly dollar-denominated. Such significant market size naturally attracts regulatory attention and innovation, mirroring the attention seen in other crypto products.
Regulatory frameworks, such as the Market in Crypto-Assets Regulation (MiCA) in the EU, which saw partial implementation in June 2024, are shaping how stablecoins operate. MiCA sets clear rules for crypto assets and requires fiat-backed tokens to maintain 1:1 liquid reserves.
The UK is also developing its own specific regime for stablecoins, with proposals from both the Financial Conduct Authority (FCA) and the Bank of England.
Jurisdictions like Jersey, where Lloyds’ Corporate Markets branch booked the payment obligations, are also playing a key role. Jersey is a self-governing Crown Dependency with a well-established finance industry and a regulatory environment that supports digital asset innovation. The regulatory clarity and robust oversight in such hubs are vital for the continued growth and institutional adoption of digital assets.
Outlook: Incremental Integration, Not Wholesale Disruption
While the Lloyds Banking Group and Visa pilot used real payment obligations, the companies have yet to announce a timetable for commercial deployment. This cautious approach is characteristic of major financial institutions as they navigate the complexities of integrating nascent technologies with established systems. The focus remains on strategic exploration rather than immediate, large-scale implementation.
The pilot underscores a broader trend: traditional finance isn’t looking for wholesale disruption from digital assets but rather incremental integration to solve specific pain points. The ability to manage liquidity more effectively, accelerate cross-border transfers, and operate 24/7 are tangible benefits that stablecoins offer. This measured integration signals a future where digital assets complement, rather than completely replace, traditional banking infrastructure.