
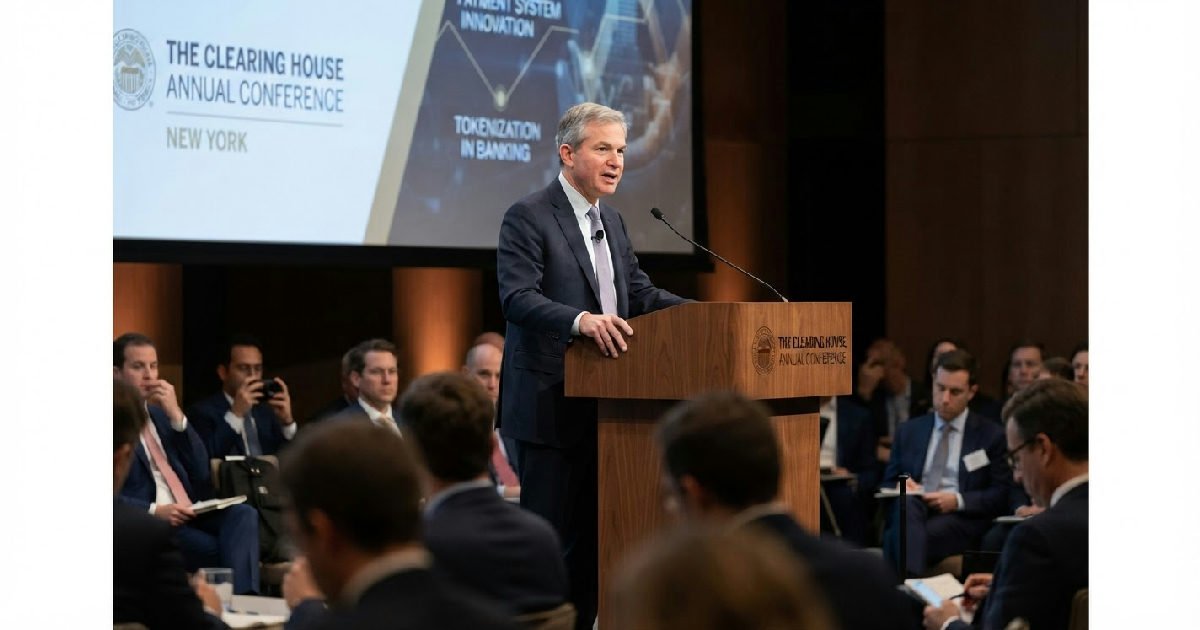
federal reserve governor christopher j waller speaks
Federal Reserve Governor Christopher J. Waller stated that blockchain and tokenization are revolutionizing payments, forcing traditional banks to compete. Waller, speaking at a major industry conference, declared that blockchain technology and tokenization are creating a “revolution in payments” that is actively forcing traditional banks to compete.
His remarks signal a clear acknowledgment from the highest levels of U.S. finance that decentralized systems are now a serious challenge to the established order.
Speaking at The Clearing House Annual Conference in New York on November 17, 2026, Waller asserted that the long-standing monopoly held by the banking system is finally breaking down. He pointed to new technologies and new entrants offering payment services outside the conventional financial rails as the primary drivers of this shift.
Reserve Governor Christopher on banking’s dominance
Waller described the current moment as a pivotal one for finance. “We’re going through a revolution in payments that we have not seen for a long, long time,” he stated. This change is driven by the emergence of new payment instruments and technologies operating independently of the banking system.
For decades, banks have controlled the primary rails for moving money. But according to Waller, that is changing rapidly. “The banking system for most of the time has pretty much a monopoly. But that’s breaking down,” he explained, highlighting the competitive pressure from these new platforms.
This isn’t just about fintech apps offering better user interfaces. The challenge runs deeper, targeting the very infrastructure of finance. Waller noted that these new technologies are compelling established firms to adapt quickly or risk being left behind in a rapidly evolving landscape.
How blockchain provides a new competitive edge
The core of this new competition lies in the unique features of blockchain technology. “Blockchains in particular have some distinguishing features that make them ripe ground for competition in payments and financial markets,” Waller observed. One of the most significant is their constant availability.
“By operating 24/7/365, open blockchain networks offer a new paradigm for competition with traditional payment rails,” he said. This directly contrasts with conventional systems that often shut down for weekends and holidays, creating settlement delays that blockchain can eliminate.
He also pointed to the open-source nature of smart contracts, which allows developers to build and launch financial services without needing to create an entire payment network from scratch. This drastically lowers the barrier to entry for innovators looking to create new products and services.
To illustrate the power of programmable settlement, Waller described a scenario where an investor could buy a tokenized stock on a Saturday. The asset and the payment could be programmed to exchange hands simultaneously, removing the counterparty risk and delays inherent in today’s markets.
A multi-asset future for digital payments
Governor Waller does not see a single winner in this new financial ecosystem. Instead, he envisions a future where multiple types of digital assets coexist to serve different functions. This includes stablecoins, tokenized bank deposits, and tokenized money market funds.
He suggested that institutional users, like corporate treasurers, would likely use different instruments for different needs. One token might be used for international payments, while another could be preferred for securities transactions, with the choice depending on regulation and existing financial connections. It’s a vision that aligns with the growing trend of major banks increasing their exposure to the digital asset class.
Waller noted that this shift is already underway. He mentioned that The Clearing House, the very organization hosting the conference, is developing a network to clear and settle tokenized deposits. At the same time, stablecoins are starting to be used behind the scenes for settlement within major card networks.
Unresolved questions and the specter of ‘zombie chains’
Despite his optimism about competition, Waller was direct about the significant hurdles that remain. Before tokenized finance can achieve mainstream adoption, he stressed that critical questions of liability and governance must be answered. These are not trivial concerns for institutional players.
Who is responsible when a smart contract is exploited or contains a bug that leads to losses? What happens when a user loses their private keys, effectively losing access to their assets forever? Waller raised these issues as fundamental challenges to building trust in the new systems.
He also warned of the risk of “zombie chains”—failed blockchain projects that cease development and lose their user base. Assets tokenized on such networks could become stranded and worthless, creating a significant risk for investors. Such events often lead to regulatory probes into token volatility and project failures.
Waller argued that reliable technology is not sufficient on its own. The industry needs robust governance frameworks, clear legal protections, and common standards for custody and settlement. Without these, mainstream institutions will remain hesitant to fully commit to the tokenized economy.
Waller’s consistent push for financial competition
His speech on November 17 was not an isolated event but the continuation of a long-held position. For years, Governor Waller has been one of the most vocal advocates within the Federal Reserve for allowing more competition in the financial sector, particularly from crypto and fintech firms.
In a November 2021 speech, he challenged proposals that would have restricted stablecoin issuance to incumbent banks. He argued that such a move would eliminate the competitive pressure that stablecoins could place on banks, ultimately harming consumers and innovation. This stance has informed discussions around corporate Bitcoin strategies and their access to the banking system.
More recently, in October 2025, Waller proposed the creation of “skinny” master accounts at the Federal Reserve. These limited-purpose accounts would give crypto and fintech firms access to the Fed’s payment services without granting them the full privileges of a traditional bank, a move met with concern by some in the banking industry.
The foundational role of central bank money
While Waller champions competition from new technologies, he remains firm on one point: central bank money must remain the ultimate foundation of the financial system. He does not believe it needs to be used in every single transaction, but its role as an “essential anchor” for final settlement is non-negotiable.
In his view, the Federal Reserve’s role is to provide stable settlement infrastructure, monitor for financial stability risks, and engage with the industry. He sees the central bank as a convener that can help the market solve problems where it is unable to do so on its own.
Ultimately, Waller’s comments paint a picture of an evolving financial landscape. It’s one where the innovation and efficiency of blockchain technology are welcomed as a competitive force, but where the stability and trust of the traditional system, anchored by the central bank, remain paramount.