
Morgan Stanley forecasts further China stock market downturn
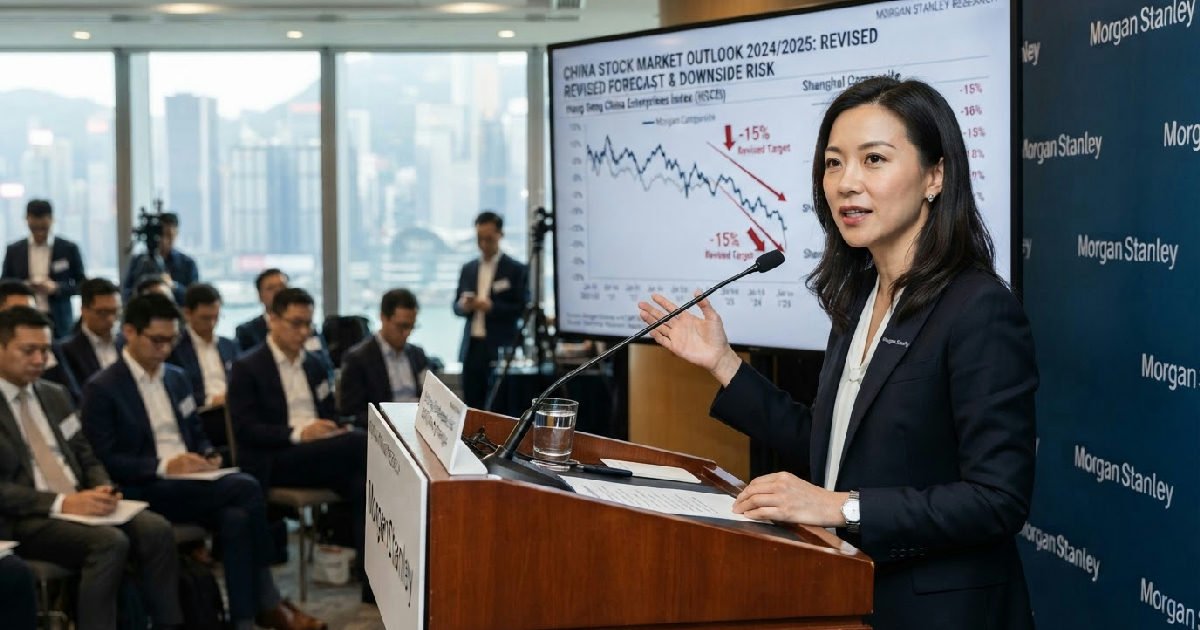
Morgan Stanley has delivered a sobering forecast for China’s equity markets, advising investors to brace for further declines before any significant recovery. The multinational investment bank announced a comprehensive cut to its target prices for major mainland China and Hong Kong stock indices on September 4, 2026. This pessimistic outlook is primarily driven by persistent macroeconomic weaknesses and diminishing support from liquidity conditions.
Analysts, including Laura Wang, detailed their revised perspective in a report published on September 10, 2026. They project that offshore shares could fall another 10% to 15% before reaching historical valuation levels. Mainland-listed equities are expected to experience a similar de-rating, hitting approximately 10 to 11 times forward earnings.
Morgan Stanley’s China stock market forecast
The latest adjustment marks Morgan Stanley’s second downgrade to its China and Hong Kong equity outlook since May 2026, reflecting a deepening concern among financial institutions. The bank’s revised base-case targets, set as of the end of June 2026 but announced in September, paint a clear picture of anticipated market contraction.
The Hang Seng Index (HSI) target was lowered to 26,550 points, an approximately 6.5% reduction from its previous 28,400-point forecast. Similarly, the Hang Seng China Enterprises Index (HSCEI) saw its target drop to 8,900 points from 9,900. The MSCI China Index is now projected to hit 80 points, down from 91, while the CSI 300 Index target fell to 4,880 points from 5,400.
These revised targets imply a modest upside potential of only 5% to 7% for major Chinese indices. Such limited growth prospects underscore the challenging environment investors currently face. It also highlights the bank’s cautious stance on a market once considered a growth engine.
Economic Headwinds Batter Chinese Economy
A primary driver behind Morgan Stanley’s bleak forecast is the relentless onslaught of weakening macroeconomic data from China. The nation’s economic recovery trajectory has slowed significantly, impacting corporate earnings and investor confidence. This softness is broad-based, affecting various sectors.
Official data for the first eight months of 2026 showed fixed-asset investment falling by 7.2%, a clear signal of reduced capital expenditure. Furthermore, monthly growth in retail sales has remained stubbornly below 1% for five consecutive months. This indicates a sustained weakness in consumer spending, a crucial component of China’s economic health.
The property sector, a perennial concern, continues to exhibit fragility. Morgan Stanley had already noted on June 11, 2026, that 25-city secondary real-time home sales softened to 9.2% year-over-year month-to-date as of June 10, 2026. This compared unfavorably to 30% in April and 26% in May.
The firm has maintained a cautious stance on the property sector, believing its risks outweigh potential rewards. Investors are clearly watching the property sector for any signs of broader economic contagion.
The slower earnings recovery trajectory, resulting from downgraded GDP forecasts, further compounds these challenges. Companies are finding it harder to meet revenue and profit expectations. This directly impacts stock valuations, leading to the de-rating observed across both offshore and mainland equity markets. It’s a cyclical problem where weak economic data fuels lower earnings, which in turn suppresses market enthusiasm.
The prevailing economic conditions represent a significant shift from previous growth expectations. Many analysts are now re-evaluating their long-term growth models for China. The slowdown affects not just domestic sentiment but also global supply chains and trade partners. Changing consumer demand in China directly impacts international brands operating there.
Liquidity and Capital Flow Squeeze
Beyond macroeconomic concerns, Morgan Stanley’s analysis points to diminished support from liquidity conditions as a significant factor. Tighter capital flow prospects, coupled with mainland authorities’ stepped-up capital flow regulation, are restricting market maneuverability. This creates an environment less conducive to equity market growth.
The Hong Kong market faces additional pressures from ongoing Initial Public Offering (IPO) supply and lock-up share expiries. These events can flood the market with new shares, diluting existing holdings and exerting downward pressure on prices. It’s a structural issue that adds to short-term volatility.
External factors, particularly the increasingly hawkish expectations for the U.S. Federal Reserve, also play a role. A stronger dollar and higher U.S. interest rates can draw capital away from emerging markets, including China. This further exacerbates liquidity concerns and makes Chinese assets less attractive to international investors. The interplay between global monetary policy and local market dynamics is complex.
These liquidity challenges aren’t just theoretical; they manifest in actual trading activity. Data from September 9, 2026, showed a decline in the average daily turnover (ADT) of the ChiNext Board by 8% to RMB 473 billion compared to the previous week. The free-float market capitalization of A-shares also decreased by 6% to RMB 1.913 trillion. Such metrics provide tangible evidence of reduced market activity.
However, some pockets of activity remain. Trading volume in stock index futures rose by 5% to RMB 417 billion, suggesting some hedging or speculative interest. The balance of margin financing and securities lending remained stable at RMB 2.611 trillion. This indicates that while outright buying activity is low, leveraged positions aren’t collapsing. Investor positioning can impact market movements across various asset classes.
Investor Positioning and Market Performance
The normalization of investor positioning from previously extreme underweight levels is another nuanced point in Morgan Stanley’s assessment. While this might seem positive on the surface, it actually reduces the room for additional inflows. When investors are already at a more neutral position, there’s less pent-up demand to drive prices higher. This means any positive news has a muted impact on buying activity.
Chinese equity indices have indeed seen significant declines throughout 2026. The MSCI China Index, a key barometer for international investors, has lost almost 14% since the beginning of the year. This puts it squarely on the cusp of a bear market, a classification often applied after a 20% decline from recent highs.
The CSI 300 index, which tracks mainland A-shares, has also suffered, shedding 15% since June 22, 2026.
Morgan Stanley’s A-share Sentiment Indicator (MSASI) reflects this cautious mood. As of September 9, 2026, the MSASI declined by 1 percentage point to 20% from the prior cutoff date of September 2. Although the 1-month moving average remained unchanged at 31%, the week-over-week drop indicates a subtle but important shift in immediate investor sentiment.
The 30-day Relative Strength Index (RSI) did increase by 4 percentage points, suggesting some short-term oversold conditions might be easing, but not enough to counteract the broader bearish trend.
This sustained period of underperformance challenges previous long-term growth narratives. Many investors had viewed China as an indispensable component of their portfolios. Now, the prolonged downturn forces a re-evaluation of that assumption, prompting a more selective and cautious approach to Chinese assets. It’s a period of recalibration for global investment strategies.
Broader Implications for Global Markets
The continued weakness in the China stock market, as predicted by Morgan Stanley, carries significant implications beyond Beijing and Hong Kong. China’s economic might and its interconnectedness with global trade mean that its financial health reverberates worldwide. A prolonged downturn in Chinese equities could signal broader economic fragility.
Global corporations with substantial exposure to the Chinese consumer market or manufacturing supply chains face potential headwinds. Slower economic growth in China translates to reduced demand for imports and lower factory output, affecting companies from raw material suppliers to luxury goods manufacturers. Investment decisions by international firms operating in China may become more conservative, impacting foreign direct investment flows.
Furthermore, China’s financial markets are increasingly integrated into the global system. Volatility in Shanghai or Hong Kong can spill over into other emerging markets and even developed economies. This creates a challenging environment for global portfolio managers seeking stability. Global e-commerce trends often hinge on Chinese market performance and consumer behavior.
The cautious stance from a major bank like Morgan Stanley influences institutional investor behavior. Their downgrades can trigger further sell-offs or deter new investments, creating a self-fulfilling prophecy. This herd mentality, while rational from an individual investor