
General Motors narrows 2026 earnings outlook
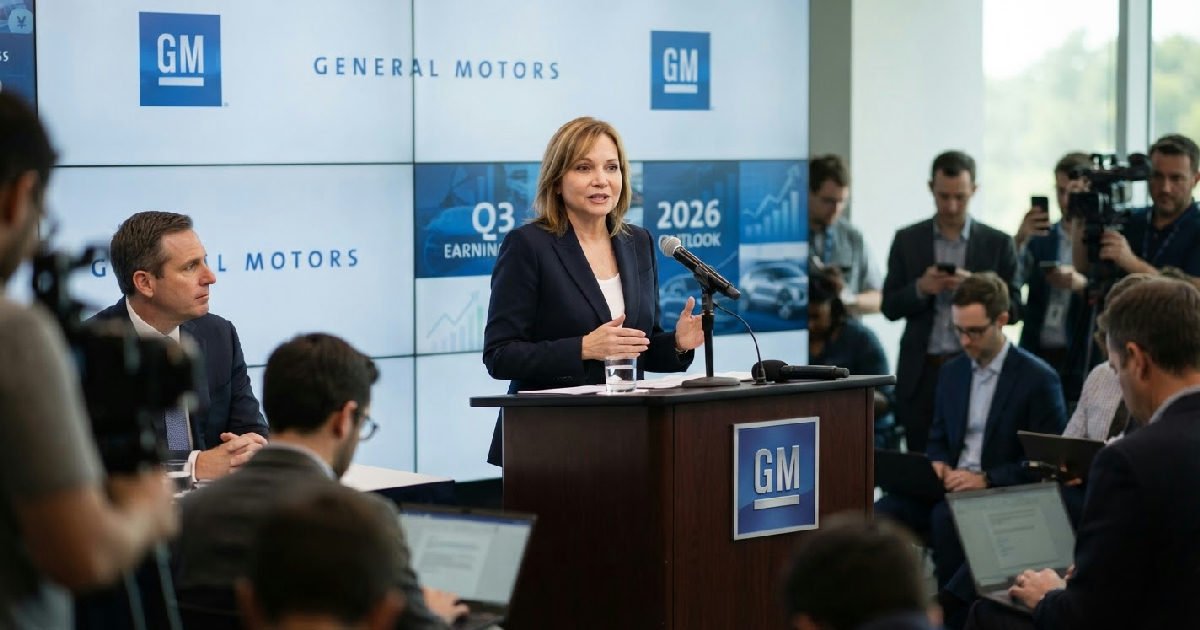
General Motors (GM) posted third-quarter 2026 earnings on Tuesday that surpassed Wall Street expectations, driven by the enduring strength of its traditional truck and SUV sales. The Detroit-based automaker reported revenues of $50.02 billion and an adjusted earnings per share of $3.70, alongside a massive new $20 billion share repurchase program.
The results prompted GM to narrow its full-year profit guidance and significantly raise its free cash flow forecast.
General Motors earnings guidance and shareholder returns
Despite the strong financial performance, the broader market reaction was not immediately clear, with analysts considering the persistent inflationary pressures and a notable decline in electric vehicle sales. The results, announced after a conference call hosted by CEO Mary Barra and CFO Paul Jacobson, highlight a company excelling in its established vehicle segments while navigating considerable challenges in its pivot towards an all-electric future.
In the wake of its strong quarter, General Motors adjusted its financial outlook for the full year. The company now expects adjusted earnings before interest and taxes (EBIT) to be between $14.5 billion and $15.5 billion.
This tightens the previous range of $14.0 billion to $16.0 billion, signaling greater certainty for the remainder of the year. Similarly, the forecast for adjusted earnings per share was narrowed to between $12.75 and $13.75, from a prior $12.00 to $14.00.
Perhaps the most significant update was the boost to its adjusted automotive free cash flow projection. GM raised this crucial metric to a range of $11.5 billion to $12.5 billion for the year, a substantial increase from the previous guidance of $9.5 billion to $11.5 billion.
This highlights the company’s powerful cash-generating capabilities, largely fueled by its North American operations. The persistent issue of US producer inflation continues to be a factor for manufacturers, but GM’s strong cash flow provides a substantial buffer.
Bolstering this confidence, GM’s board approved a new, multi-year share repurchase authorization for $20 billion, which carries no expiration date. This follows the recent completion of a $6 billion buyback program initiated in January. The company also declared a quarterly cash dividend of $0.18 per share, underscoring its commitment to returning capital to shareholders.
These actions reflect a management team confident in its financial stability and future earnings potential, even as it navigates a complex market.
Traditional pickups continue to drive profits
The financial strength demonstrated in the third quarter largely stemmed from GM’s domestic market. While the total adjusted EBIT reached $4.1 billion for the quarter, details on specific regional contributions to this figure were not fully detailed in the recent announcements.
The success was significantly underpinned by its light-duty pickup trucks, with sales increasing by 9.3% in the quarter. Notably, the Chevrolet Silverado’s light-duty sales climbed 13.3% to 100,221 units.
This robust demand for high-margin trucks provides the financial engine for the entire company. It funds the massive share buybacks, the consistent dividends, and the costly research and development required for the EV transition.
While the industry shifts toward electric, GM’s results show that for now, traditional internal combustion engines are paying the bills and keeping investors happy. This reliance on a legacy product line is a common theme, with competitors like the Daimler Truck financial arm also managing a transition from a position of strength in conventional vehicles.
Electric vehicle ambitions hit a wall
The story for GM’s electric vehicles could not be more different. U.S. sales of its EVs plummeted by a staggering 62% in the third quarter, totaling just 25,500 units.
This figure represents less than 4% of the company’s total sales volume in the period, a worrying sign for a company that has staked its future on electrification. The slowdown underscores a broader cooling in the EV market as consumers weigh high prices and charging infrastructure concerns.
The decline was particularly severe for the Chevrolet Equinox EV, a model once highlighted as a crucial mainstream offering, with its sales dropping by 92.4% year-over-year. General Motors has acknowledged the ongoing challenges in its electric vehicle strategy, which included a pullback on certain EV initiatives last year.
While the company continues to manage the financial implications of this strategic shift, specific figures for related charges were not detailed in the latest earnings report.
Navigating economic headwinds and rising costs
While the headline financial results were positive, General Motors remains subject to broader economic pressures impacting the manufacturing sector. The company has indicated that inflationary costs continue to be a factor, though specific figures for commodity inflation or detailed breakdowns of affected components were not provided in the current financial release. These broader economic headwinds affect many players across various industries.
Despite the positive earnings, the company’s outlook on managing inflationary pressures remains a key point of focus for investors. Management has emphasized efforts towards operational efficiency and strategic investments to maintain momentum. The broader market reaction often reflects a balance between strong current profits and concerns over the evolving electric vehicle market, alongside the persistence of elevated input costs.
This dynamic is not unique to GM, as many major corporations, including those highlighted in HDFC Bank earnings reports, are navigating a complex environment of rising costs and shifting consumer demand. The broader management of operational expenses will remain crucial for General Motors in maintaining its profitability targets.
International performance and forward outlook
GM’s third-quarter results underscore its heavy reliance on the North American market. While its domestic operations generated billions, its international segments were far more modest. GM International contributed just $28 million in adjusted EBIT, while the company’s China equity income was only $32 million for the quarter. This geographical concentration makes GM particularly sensitive to the economic health and consumer trends of the U.S. market.
The company’s financing arm, GM Financial, remains a stable contributor, posting adjusted earnings before taxes of $668 million. However, the primary focus for investors moving forward will be on the company’s ability to translate its EV strategy into sales volume and profitability.
The current strength of the truck and SUV market provides a powerful financial foundation, but it cannot last indefinitely as global emissions regulations tighten.
The key question for General Motors is whether it can successfully navigate this transition. Can it leverage the immense profits from its legacy business to fix its EV lineup, regain market share, and convince both consumers and investors that its all-electric future is still on track?
The coming quarters will be critical in determining if the current EV slump is a temporary setback or a sign of deeper strategic problems.