
Oil price and Treasury yield correlation hits
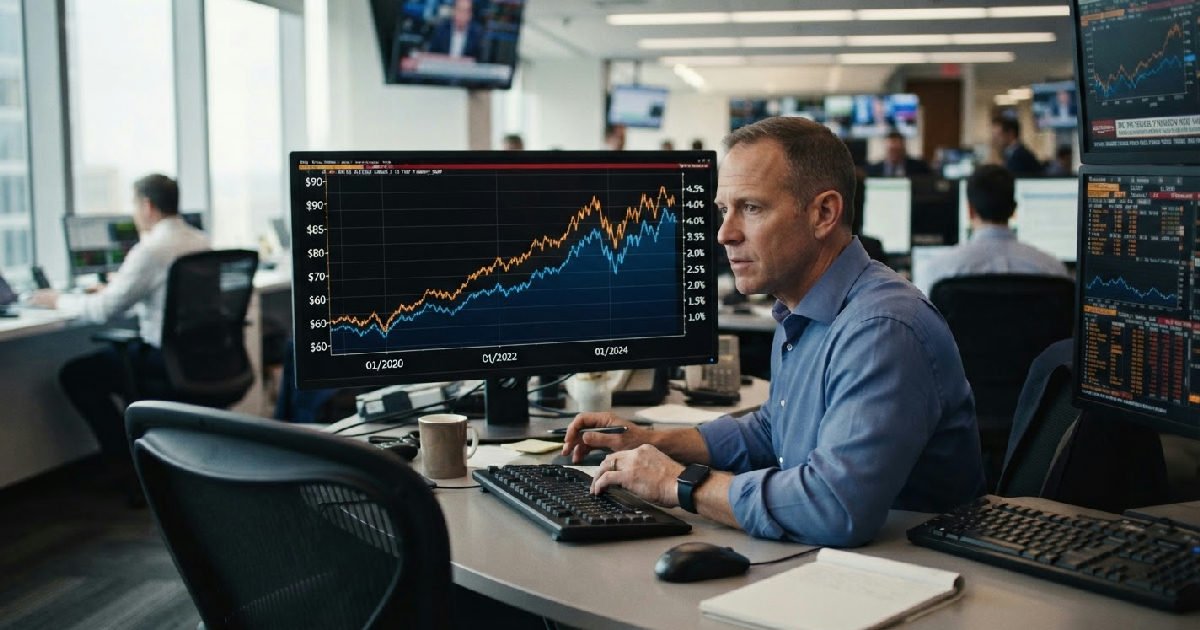
An alarming alignment between oil and treasury yields correlation is sending tremors through global financial markets. The one-month rolling correlation between West Texas Intermediate (WTI) crude and the 10-year U.S. Treasury yield has surged to 0.96, a level of lockstep movement not seen in seven years, according to data from BMO Capital Markets.
This tightening relationship, the strongest since June 2019, is being fueled by a toxic combination of events. Geopolitical conflict in the Middle East has sent oil prices soaring, with Brent crude topping $108 a barrel on September 14. Simultaneously, the benchmark 10-year Treasury yield briefly crossed 5% for the first time since October 2023, signaling intense anxiety over persistent inflation and future interest rate hikes.
Oil and treasury yields correlation’s toxic cocktail
The near-perfect correlation means that shocks in the energy market now transmit almost directly into the wider financial system, creating a perilous feedback loop. Traditionally, bonds might offer a safe haven during periods of equity stress, but this dynamic breaks down when yields are rising in tandem with the very commodity driving the uncertainty.
“The main impact is that an oil shock now transmits more directly into financial conditions,” said Billy Leung, investment strategist at Global X ETFs. He explained that a continued rise in crude prices could lift inflation expectations, thereby delaying any potential easing of monetary policy by the Federal Reserve and raising the discount rate used to value stocks and credit.
This environment is particularly punishing for equity markets. Higher Treasury yields increase the opportunity cost of owning stocks, making the guaranteed return from government debt more attractive. At the same time, a sharp oil price surge squeezes corporate profit margins, especially for companies heavily reliant on energy and transportation.
Technology and other growth stocks are acutely vulnerable. Their valuations are often based on earnings projected far into the future. When interest rates and yields rise, the present value of those future earnings is diminished, putting downward pressure on their share prices.
Federal Reserve cornered as rate hike odds climb
This market turmoil places central bankers, particularly at the U.S. Federal Reserve, in a difficult position. The primary driver of the high correlation—surging oil prices—is an inflationary force that the Fed cannot ignore. The market is taking note, with traders pricing in an 88.9% probability of another quarter-point interest rate hike at the Fed’s meeting on September 16, according to LSEG data.
Analysts warn that this may not be the end of the tightening cycle. Ed Yardeni, president of Yardeni Research, believes the situation is grim. “It’s certainly bad news that if oil prices continue to move higher, that would indicate that bond yields are moving higher,” he said.
This, he argues, raises inflationary expectations and “the odds that we’ll be in a tightening cycle… there could be two or three rate hikes up ahead here.”
Such a scenario, Yardeni added, would be “unsettling for the stock market.” The Fed is thus caught between fighting commodity-driven inflation and risking a deeper economic slowdown by making borrowing costs prohibitively expensive. A recent $6 billion bond buyback by the Treasury Department did little to soothe frayed nerves in the bond market, highlighting the scale of the challenge.
Consumers and businesses feel the double-edged sword
The macroeconomic anxieties are not confined to trading floors. Consumers and businesses are facing a painful “double hit,” as described by Andy Lipow, president of Lipow Oil Associates. Higher energy prices translate directly into higher costs at the gasoline pump and indirectly into the price of goods and services that rely on transport.
Simultaneously, rising Treasury yields ripple through the economy, pushing up rates for mortgages, auto loans, and other forms of credit.
“Both increase in the WTI crude price, along with the increase in the treasury yield, are bad news for the consumer,” Lipow stated plainly. This dual pressure erodes household purchasing power and can lead to a pullback in consumer spending, a primary driver of the U.S. economy.
Businesses face a similar squeeze. Higher yields raise the cost of financing everything from daily inventory to long-term capital investments. Lipow noted this could weigh on capital-intensive projects, including the massive buildout of data centers and energy infrastructure needed to support new technologies, even as the AI boom fuels hopes for productivity gains.
The spectre of a bond bear market
Some strategists believe the current environment marks the beginning of a prolonged downturn for bonds. Komal Sri-Kumar, president of Sri-Kumar Global Strategies, has already declared the arrival of a “bond bear market” with yields headed up. “I don’t see anything that stops the upward march of oil and natural gas prices either,” he said, signaling a bleak outlook for both asset classes.
In response, Sri-Kumar is advising clients to steer clear of assets most vulnerable to higher interest rates, such as technology growth stocks. He favors short-duration fixed income, which is less sensitive to rate changes, and defensive equities.
He also recommends physical assets like real estate, copper, and gold as potential hedges against persistent inflation, a strategy gaining traction amid the jitters that have contributed to a slide in global stock markets.
The historical context for this correlation is complex. The relationship began to strengthen significantly after the 2008 financial crisis. It’s partly driven by the ‘petrodollar’ system, where oil is priced in U.S. dollars and oil-exporting nations recycle those dollars by purchasing U.S. Treasurys. When demand is strong, both oil prices and yields can rise together; in a recession, both typically fall.
A fragile and potentially fleeting relationship
While the 0.96 correlation figure is stark, some analysts urge caution, suggesting the unusually tight link may not last. Billy Leung of Global X ETFs noted the relationship could “unwind rapidly” if geopolitical tensions in the Middle East were to ease or if fears of a global growth slowdown begin to dominate the narrative.
Indeed, a significant economic downturn would likely crush oil demand, sending prices lower. In that scenario, investors would flock to the safety of government bonds, pushing yields down and breaking the positive correlation. For now, however, the market remains trapped between inflation fears driven by energy and the restrictive monetary policy designed to fight it.
The situation is further complicated by recent events, including Houthi militant advances that threaten the crucial Bab al-Mandeb Strait, a chokepoint for global oil shipments. As long as energy prices and bond yields continue their synchronized march upward, they will cast a long and ominous shadow over the prospects for consumers, corporations, and the global economy.